Most people afford a custom pool, which typically costs anywhere from $45,000 to over $225,000 depending on materials and features, by utilizing specific home equity products, specialized financing, unsecured loans, or paying cash, or a combination of paying cash and making up the difference with financing. Note, this is not financial advice and it depends on your individual financial situation.
Common ways to finance a custom pool
Home Equity Line of Credit (HELOC):
Allows homeowners to draw funds as the pool project progresses (which often happens in phases) using variable interest rates backed by their home equity.
Home equity loan:
Provides a fixed lump-sum payment with a predictable fixed interest rate over a longer term (up to 30 years) using the house as collateral. This is probably the most preferred method of affording a pool.
Specialized pool and home improvement lenders:
Companies like HFS Financial, Viking Capital, or Lyon Financial offer dedicated swimming pool loans (some up to $450,000) that structure disbursements around construction milestones rather than traditional lump sums. These specialized loan companies require that the pool contractor you intend to hire is vetted and part of their network, but the requirements are not very strict to be a part of their contractor network. Depending on the structure of these loans they either give you the entire lump sum, release funds in milestones for you to disburse stage payments that should align with milestones on your pool construction contract, and in rare cases they might want to pay stage payments directly to the contractor themselves.
Unsecured personal loans:
A fast option if you lack home equity or want to avoid appraisals, though they feature shorter repayment terms (2 to 7 years) and higher interest rates. Most people mention that their credit union was the best option when it came to using an unsecured loan.
Cash-out refinance:
Replaces an existing mortgage with a larger one to pull out cash, though it resets or extends the overall mortgage timeline.
Out-of-pocket savings:
Paying with liquid cash avoids interest altogether, though financial advisors often recommend keeping a separate 3-to-6-month emergency reserve untouched.
Financial requirements & financial planning tips
Credit score:
Most prime lenders look for a score of 700 or higher for the best rates, though options exist for lower scores with higher interest.
Debt-to-income ratio (DTI):
Lenders generally prefer a DTI under 43% (ideally 36% or lower).
Itemized quotes:
Reviewing separate line items for excavation, the pool shell, plumbing, electrical, decking, and fencing prevents surprise overruns.
The 10% to 15% budget buffer:
Adding an extra cushion is vital because unexpected yard excavation issues, rock removal, or permitting delays can quickly inflate labor and material costs.
Shopping around for custom pool quotes
You are in a good position right now not having made a final decision yet, and it can be difficult to know where to start, and what you should do first. Do not worry about calling local pool companies yet as the best place to start is to know where you currently stand financially first.
The ideal steps in the process might look something like this:
- Explore financial options available to you and get pre-qualified to know “how much pool” you can afford, and that, minus any budget buffer, is your budget.
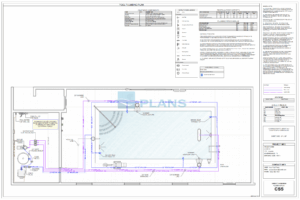
- Get with a professional pool design firm, a neutral third party that has no stake in profiting from or physically building your project, to act as your pool advisor and work through your vision to arrive at a final design where all the details are ironed out.
- You will then have a full set of pool plans all based on your vision combined with your budget that are ready to go, and that cancels out 95% of the initial back and forth stress from vetting multiple pool companies. You have one design that represents exactly what you want/can do.